Independent practical guide

Recommended Dog Insurance

Recommend a dog-insurance structure only after deciding which need must survive the exclusions.

Policy-first Independent Useful checks
Key checks

What matters on this page

Use these checkpoints to frame the literal question before reading the full guide.

Dog Age and history Actual facts first
Owner Retained-cost capacity Choose a priority
Policy Terms and selections Verify the fit
Direct answer

Recommended dog insurance should fit the dog’s history and the owner’s ability to absorb a bill. Begin with accident-and-illness protection when both categories are the concern, then test the actual exclusions, benefits and payment mechanics. This is a needs-based selection method, not a claim that one company is best for every dog.

The sections below show how to verify the answer and what can change it.

The decisive document is the exclusion beside the benefit

A coverage heading is only the beginning of the selection. Put the relevant exclusion and selected-benefit schedule alongside it. In the public Alabama-labeled Pets Best specimen, section 5 addresses pre-existing facts; section 2 identifies optional benefits. Those locations illustrate the reading method without establishing an offer in every state.

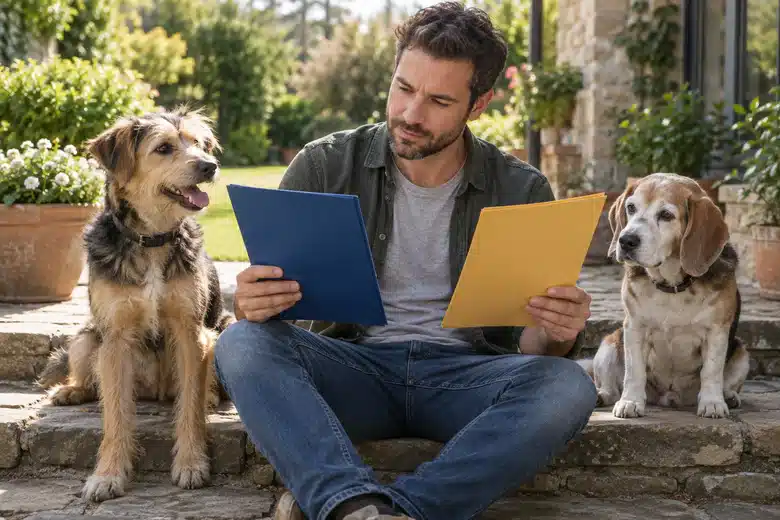
Owner outdoors with a young mixed-breed dog and an older beagle comparing plain folders
Two dogs beside a folder comparison reflect why age, history and the owner's main concern can change a shortlist.
Evidence matrix

Two dog owners, two recommendation paths

Dog and owner scenario Priority What to examine Trade-off
Hypothetical young dog, no known prior problem, limited emergency cash Large unexpected illness/injury bills Expense grant, limit, percentage, deductible and payment timing Lower premium may leave a larger retained bill
Hypothetical older dog with documented treatment and existing insurance Continuity of the known history Current renewal and proposed replacement terms A new low price cannot establish equivalent protection
Hypothetical dog with frequent separately charged consultations Exam-fee eligibility Whether the consultation option is selected A headline percentage can omit this charge

Hypothetical young dog, no known prior problem, limited emergency cash

Priority Large unexpected illness/injury bills
What to examine Expense grant, limit, percentage, deductible and payment timing
Trade-off Lower premium may leave a larger retained bill
Hypothetical older dog with documented treatment and existing insurance

Priority Continuity of the known history
What to examine Current renewal and proposed replacement terms
Trade-off A new low price cannot establish equivalent protection

Hypothetical dog with frequent separately charged consultations

Priority Exam-fee eligibility
What to examine Whether the consultation option is selected
Trade-off A headline percentage can omit this charge

These are decision scenarios rather than medical forecasts. A young dog is not guaranteed to remain healthy, and an older dog is not automatically barred from enrollment. Pets Best’s current FAQ is one example of a product stating no upper entry age. That does not decide what an earlier condition would mean for a claim.

Use one bill to expose the practical difference

Assume a fictional $3,000 invoice, $2,600 eligible expense and sufficient remaining limits. Design A pays 80% first and subtracts a $500 remaining deductible: $1,580 reimbursement and $1,420 retained bill. Design B pays 90% first and subtracts $250: $2,090 reimbursement and $910 retained bill. Premiums are deliberately unknown; these are invented designs, not company offers.

The $510 difference in payment may matter to an owner with little cash available, but it is not a complete value verdict. A different eligible base, timing restriction or premium can change the decision. Test the central concern under the actual offered contract before favoring the design that paid more in this teaching example.

Evidence matrix

The short document checklist behind a recommendation

Policy term Practical meaning Document to check
Event eligibility The owner’s central risk must fit Grant plus exclusions
Prior history Earlier facts may change the answer Definition and actual medical record
Selected fee benefits A common charge may be optional Declarations and option wording
Claim calculation Percentages alone are incomplete Formula and balance records
Continuation New enrollment and renewal are different decisions Renewal, replacement and change terms

Event eligibility

Practical meaning The owner’s central risk must fit
Document to check Grant plus exclusions

Prior history

Practical meaning Earlier facts may change the answer
Document to check Definition and actual medical record

Selected fee benefits

Practical meaning A common charge may be optional
Document to check Declarations and option wording

Claim calculation

Practical meaning Percentages alone are incomplete
Document to check Formula and balance records

Continuation

Practical meaning New enrollment and renewal are different decisions
Document to check Renewal, replacement and change terms
Compare with the details in front of you

Ready to check current rates?

Keep policy terms, deductible, reimbursement and limits beside the quote so the comparison stays consistent.

Find Coverage for Your Pet

Give each recommendation a reason and a condition

A useful conclusion could be: prioritize a design that reduces retained large-bill exposure, provided the actual premium fits the budget and the relevant event qualifies. For the already-insured dog, the conclusion could instead be: investigate renewal continuity before shopping on premium. These conditional directions help the owner make a decision without inventing a provider winner.

Checklist

Before accepting a recommendation from anyone

Ask which owner need drove the conclusion.
Check whether the recommended benefit is actually selected.
Inspect the specific form and state applicability.
Request the price inputs and date behind any cost claim.
Reject a comparison that hides an exclusion or mismatched setting.

No ranked provider panel

A public specimen can support this selection framework without a private policy. Comparable current dog offers were not assembled, so this page does not rank insurers or name a cheapest plan.

FAQ

Common questions

What should a recommendation explain?

The dog-specific need, the relevant contract evidence, the cost exposure and the remaining conditions.

Is the higher reimbursement design always better?

No. Premium, eligible expenses, limits, timing and the owner’s priorities can change the answer.

Pet Insurance Lens

Ready to compare with clearer inputs?

Keep the policy terms beside the price, then continue to rates when the comparison is clear.

See Insurance Rates